7 minute read · Ultimo Research Desk · Reviewed 5 Sept 2026
What Prop Firm Pass Rates Actually Say, and What They Do Not
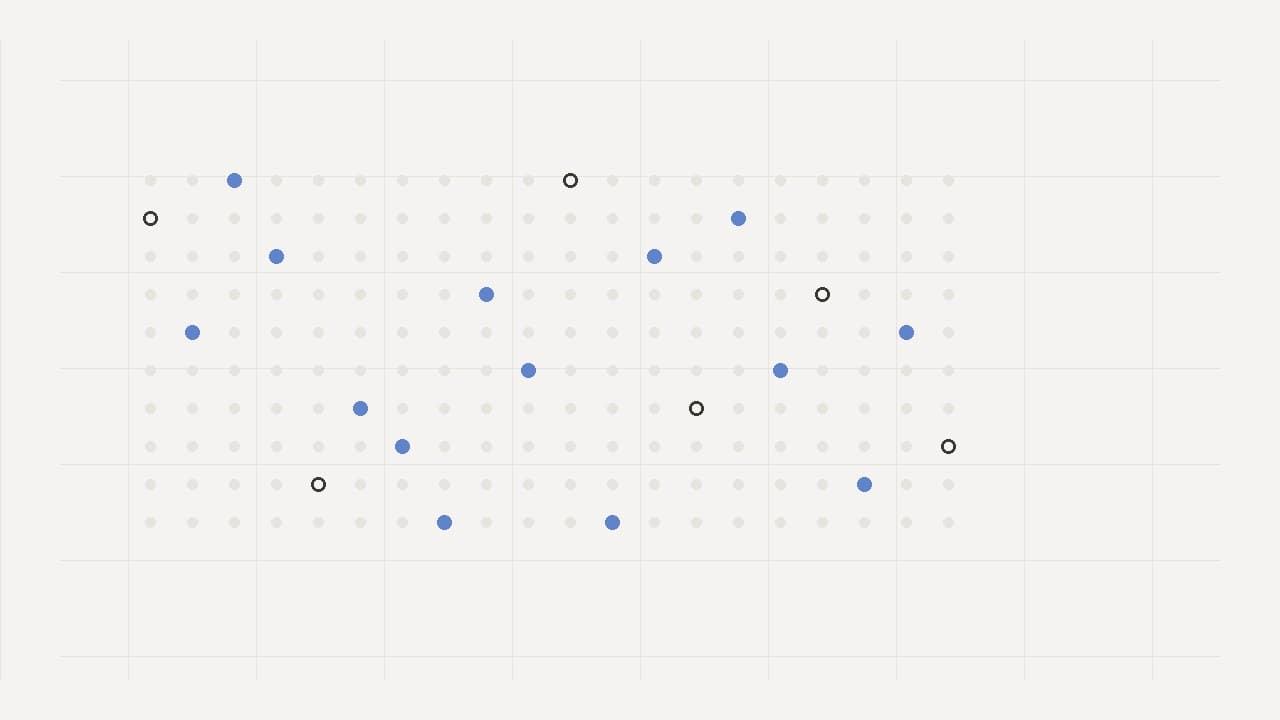
Industry estimates put the proportion of challenge accounts that are passed at between 5 and 14 per cent, and the proportion of buyers who ever receive a payout at around 7 per cent. Those two numbers are the whole economics of the category, and they are worth handling carefully — including being clear about how much confidence they deserve.
Where the figures come from
The estimates in this guide are from track360’s 2026 industry report, which puts the sector at roughly $850 million in annual revenue growing at about 45 per cent a year, with around 2.1 million funded traders, approximately 12 million challenge accounts purchased in a year, and the five largest firms taking about 62 per cent of the revenue.
They are estimates, and the distinction matters. There is no regulator collecting this data and no firm is obliged to publish it. Aggregate numbers are assembled from firms that disclose voluntarily, from payment processors and from survey work, and any figure built that way carries a margin nobody can size precisely. They are the best available picture of the category, which is not the same as a measurement of it.
We do not publish individual firms' rates. Where a firm states its own pass rate, that is an unverified claim by an interested party, and this site does not republish that class of statement about anyone.
What a 5 to 14 per cent pass rate means
Out of a hundred people who buy an evaluation, somewhere between five and fourteen complete it. Between eighty-six and ninety-five do not.
Two things follow, and the second is the one usually missed.
The first is the direct one: the expected outcome of buying an evaluation is not passing it. That is not a statement about any individual trader, in the same way that a base rate says nothing certain about one case. It is a statement about the distribution, and anybody deciding whether to spend the fee is making a decision inside that distribution whether or not they think of it that way.
The second is about repetition. A trader with a genuine 10 per cent chance per attempt has roughly a 41 per cent chance of passing at least once in five attempts, and about 65 per cent in ten. Attempts make passing more likely — and they also multiply the cost. Ten attempts at $300 is $3,000 spent for a two-in-three chance of reaching a funded account, and $3,000 is a live trading account. Which of those two is the better use of the money is a real question with no universal answer, but it is a question that should be asked in those terms rather than one attempt at a time.
What the payout figure means
Around 7 per cent of buyers ever receive a payout. Set against a pass rate of 5 to 14, the reading is that most people who pass are paid something — the payout figure sits inside the pass range rather than far below it.
That is a more reassuring picture than the one usually implied by the phrase "only 7 per cent get paid", and the honest presentation says so. The gap between passing and being paid is real but it is not the main event. The main event is the eighty-six to ninety-five who never reach the question.
It is also worth being precise about what "ever receives a payout" means: one payment, of any size, at any point. It is not a statement about how much, how often, or whether the total exceeded what the trader spent on attempts. No published figure answers that, and the absence is worth noticing, because it is the figure that would actually settle the argument.
Why the failure rate is what it is
A reasonable objection is that these numbers reflect a category selling to people who were not going to succeed at trading anyway, and that the rules are incidental.
That is partly right and does not go far enough. Three effects stack.
The first is the base rate of retail trading itself. Losing is the common outcome on a live account too, for reasons that have nothing to do with challenge rules — under-capitalisation, position sizing that cannot survive a normal losing run, and approaches that were never tested against costs. Anyone who believes a funded account would fix that is mistaking the constraint.
The second is that the rules add failure modes that live trading does not have. A daily loss limit measured from the intraday high, or a trailing drawdown that never locks, removes accounts that are ahead. That is not a moral failing of either side; it is a term of the contract, and it is why reading the rules properly is the highest-value hour in the whole process.
The third is behavioural, and it is the one that is preventable. A paid fee creates pressure to justify it. Pressure produces larger positions, trades taken to satisfy a minimum-day count, and a refusal to stop on a bad day — each of which raises the chance of hitting a limit. The fee changes how people trade, and it changes it in the direction that makes the limits more likely to be reached.
What to do with the numbers
Not, necessarily, to avoid the category. Some traders pass, are paid, and find the arrangement suits them — the capital is larger than anything they could fund themselves, and the rules impose a discipline they would not otherwise keep.
What the numbers argue against is treating an attempt as an investment with an expected return. Priced as a purchase — the cost of one attempt, multiplied by the attempts you are prepared to make, against a chance somewhere near one in ten each time — the decision is at least being made with its real terms in view.
And if the total is approaching the size of a live account, that comparison deserves to be made explicitly rather than by default. What you actually get in each arrangement sets the two side by side; what comes after a failed challenge is the more immediate question for most people reading this.
Sources
track360’s 2026 industry report. Figures are industry estimates, read on 15 September 2026, and are presented as ranges where the source gives a range.
Written by the Ultimo Research Desk and checked against our own contract specifications and client agreement before publication; reviewed again when those change. Educational only — nothing here is a recommendation to trade. Spotted an error? Tell us.